If you are thinking of buying a house or trying to lower your current loan payment, there is a recent development you should know about. The Bank of Portugal (BdP) has introduced profound changes in how loans are presented to the Portuguese, with a clear focus: to end the lack of transparency.
Since the end of March 2026, new mandatory models and forms for credit intermediaries have come into force. In practice, this means that the "fine print" that used to go unnoticed must now be shown clearly and directly.
What changes in your next simulation?
Until now, comparing offers from different banks was a headache. Each one presented the data in its own way, often omitting details that ended up making the loan more expensive months later.
With the new directive from the Bank of Portugal, intermediaries are now required to use standardized pre-information models. This ensures that:
Hidden costs appear: Insurance, opening fees, and maintenance costs must be in a format that allows you to compare "Bank A" with "Bank B" in a few seconds.
Conflicts of interest exposed: The intermediary must clearly state whether they are being paid by the bank to sell you that specific product or if they are totally independent.
The end of "isolated" proposals: It is no longer enough to be given one option; the new models encourage a comparative view of the market.
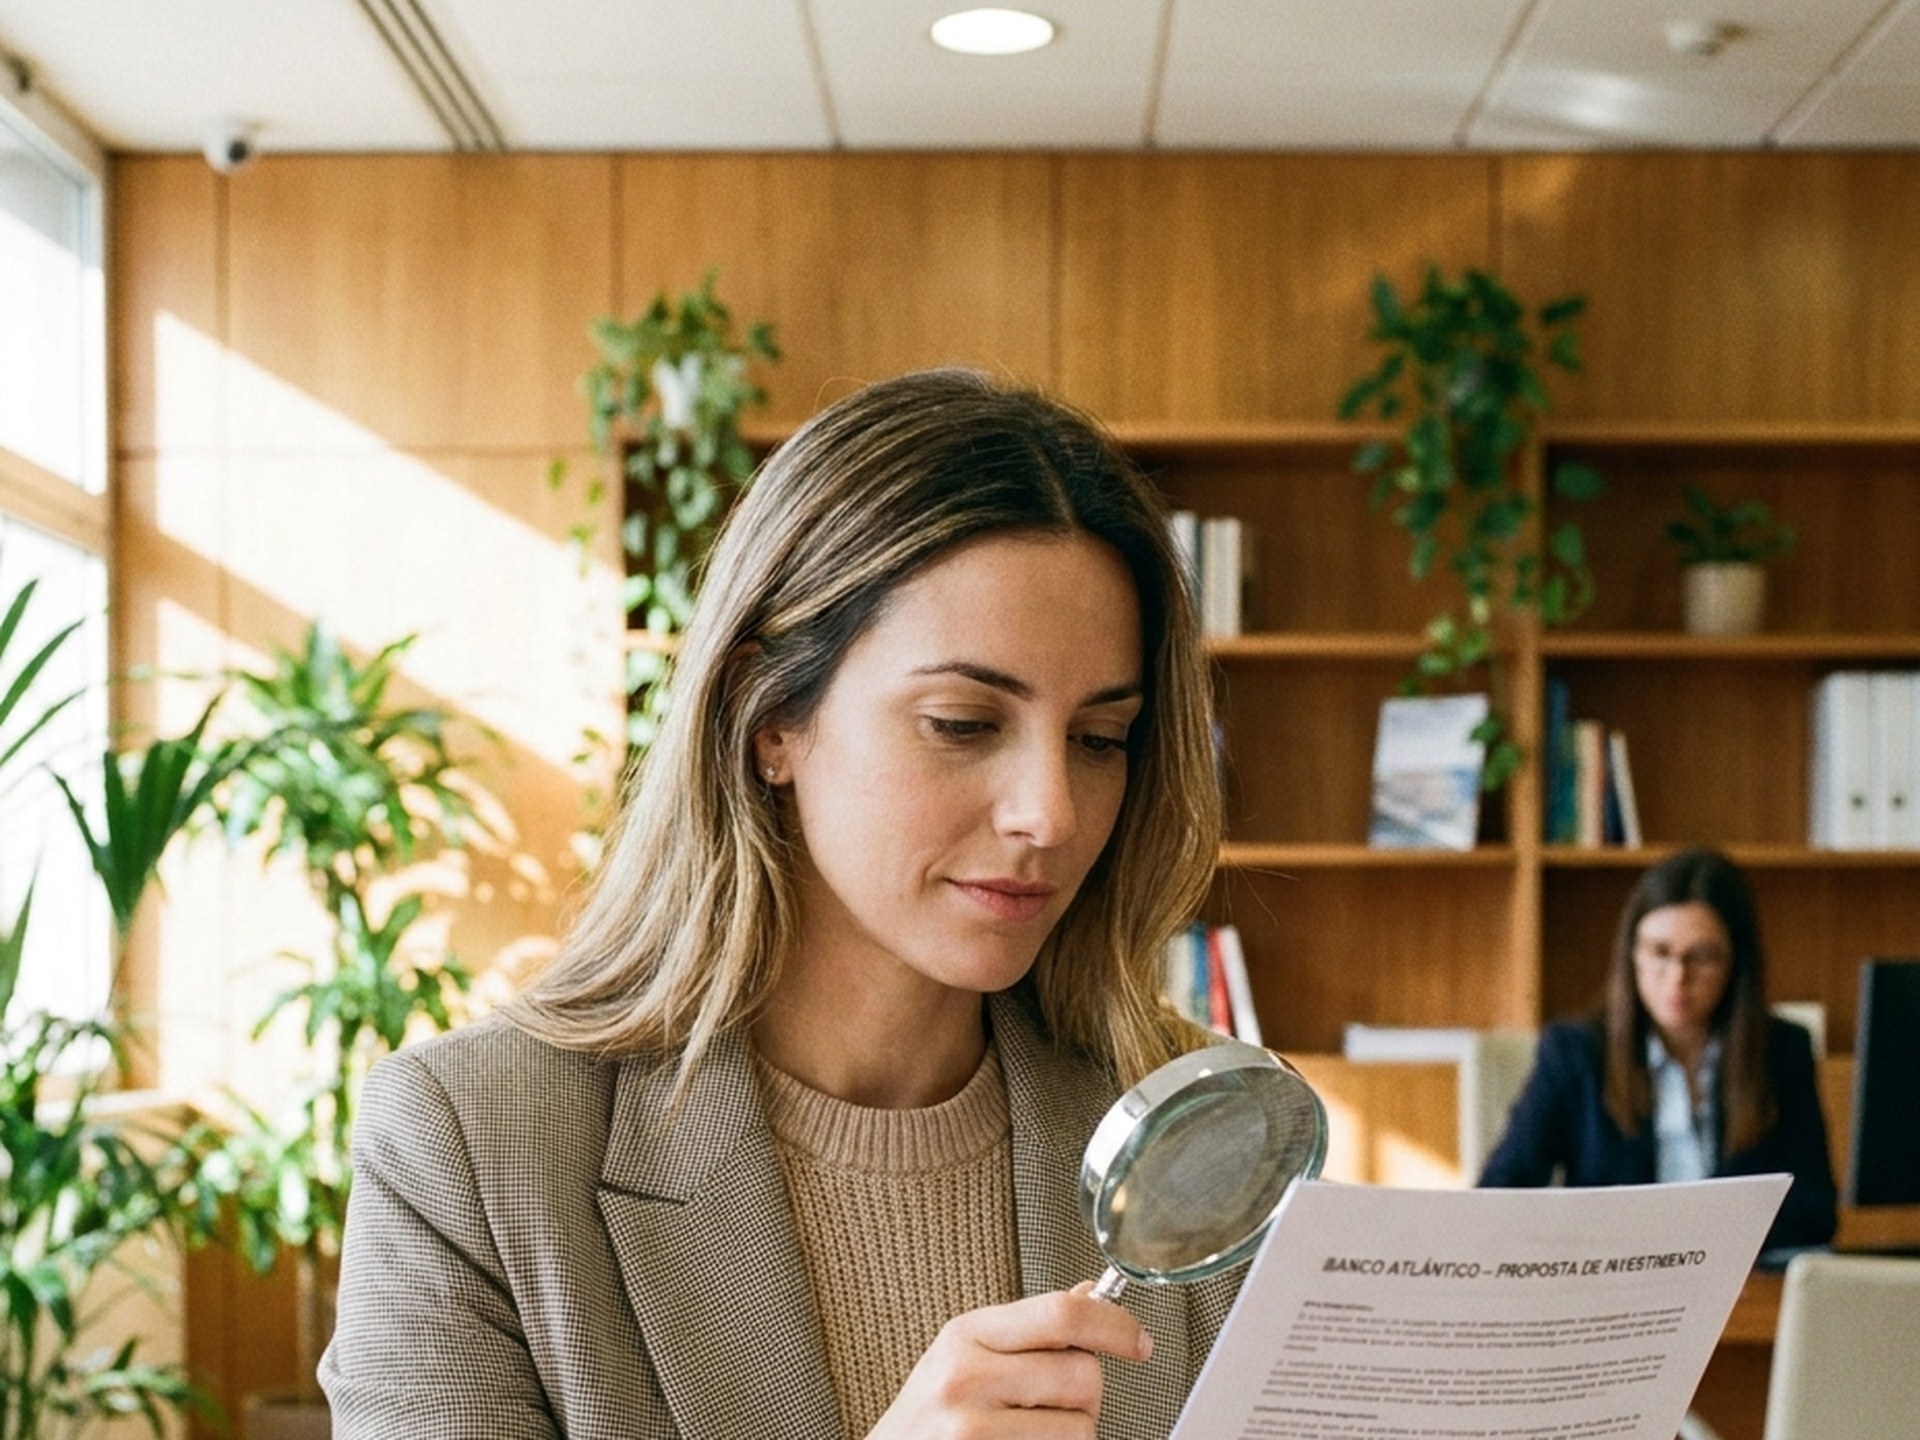
The Bank of Portugal's "magnifying glass" on the Central Credit Register
In addition to commercial transparency, there is another change (the so-called Instruction No. 1/2026) that recently came into force. The reporting of data to the Central Credit Register has become much more detailed.
What does this mean for you? When you apply for a loan, the bank now has access to a much more precise financial "X-ray". If, on the one hand, this demands more rigor from you, on the other hand, it allows good payers to get better conditions and faster responses, as the bank has fewer doubts about the risk it is taking.
In summary: Power has returned to the consumer
The regulator's message for 2026 is clear: the credit intermediation sector in Portugal has reached maturity. There is no longer room for ambiguous proposals or information given "loosely".
Practical Tip: If you ask for a simulation this week and the document you are given looks like a handwritten paper or an informal email without the official logos and forms of the Bank of Portugal, stop everything. You have the right (and now the duty) to demand the transparent information guaranteed by the 2026 law.
Share this article on your social networks