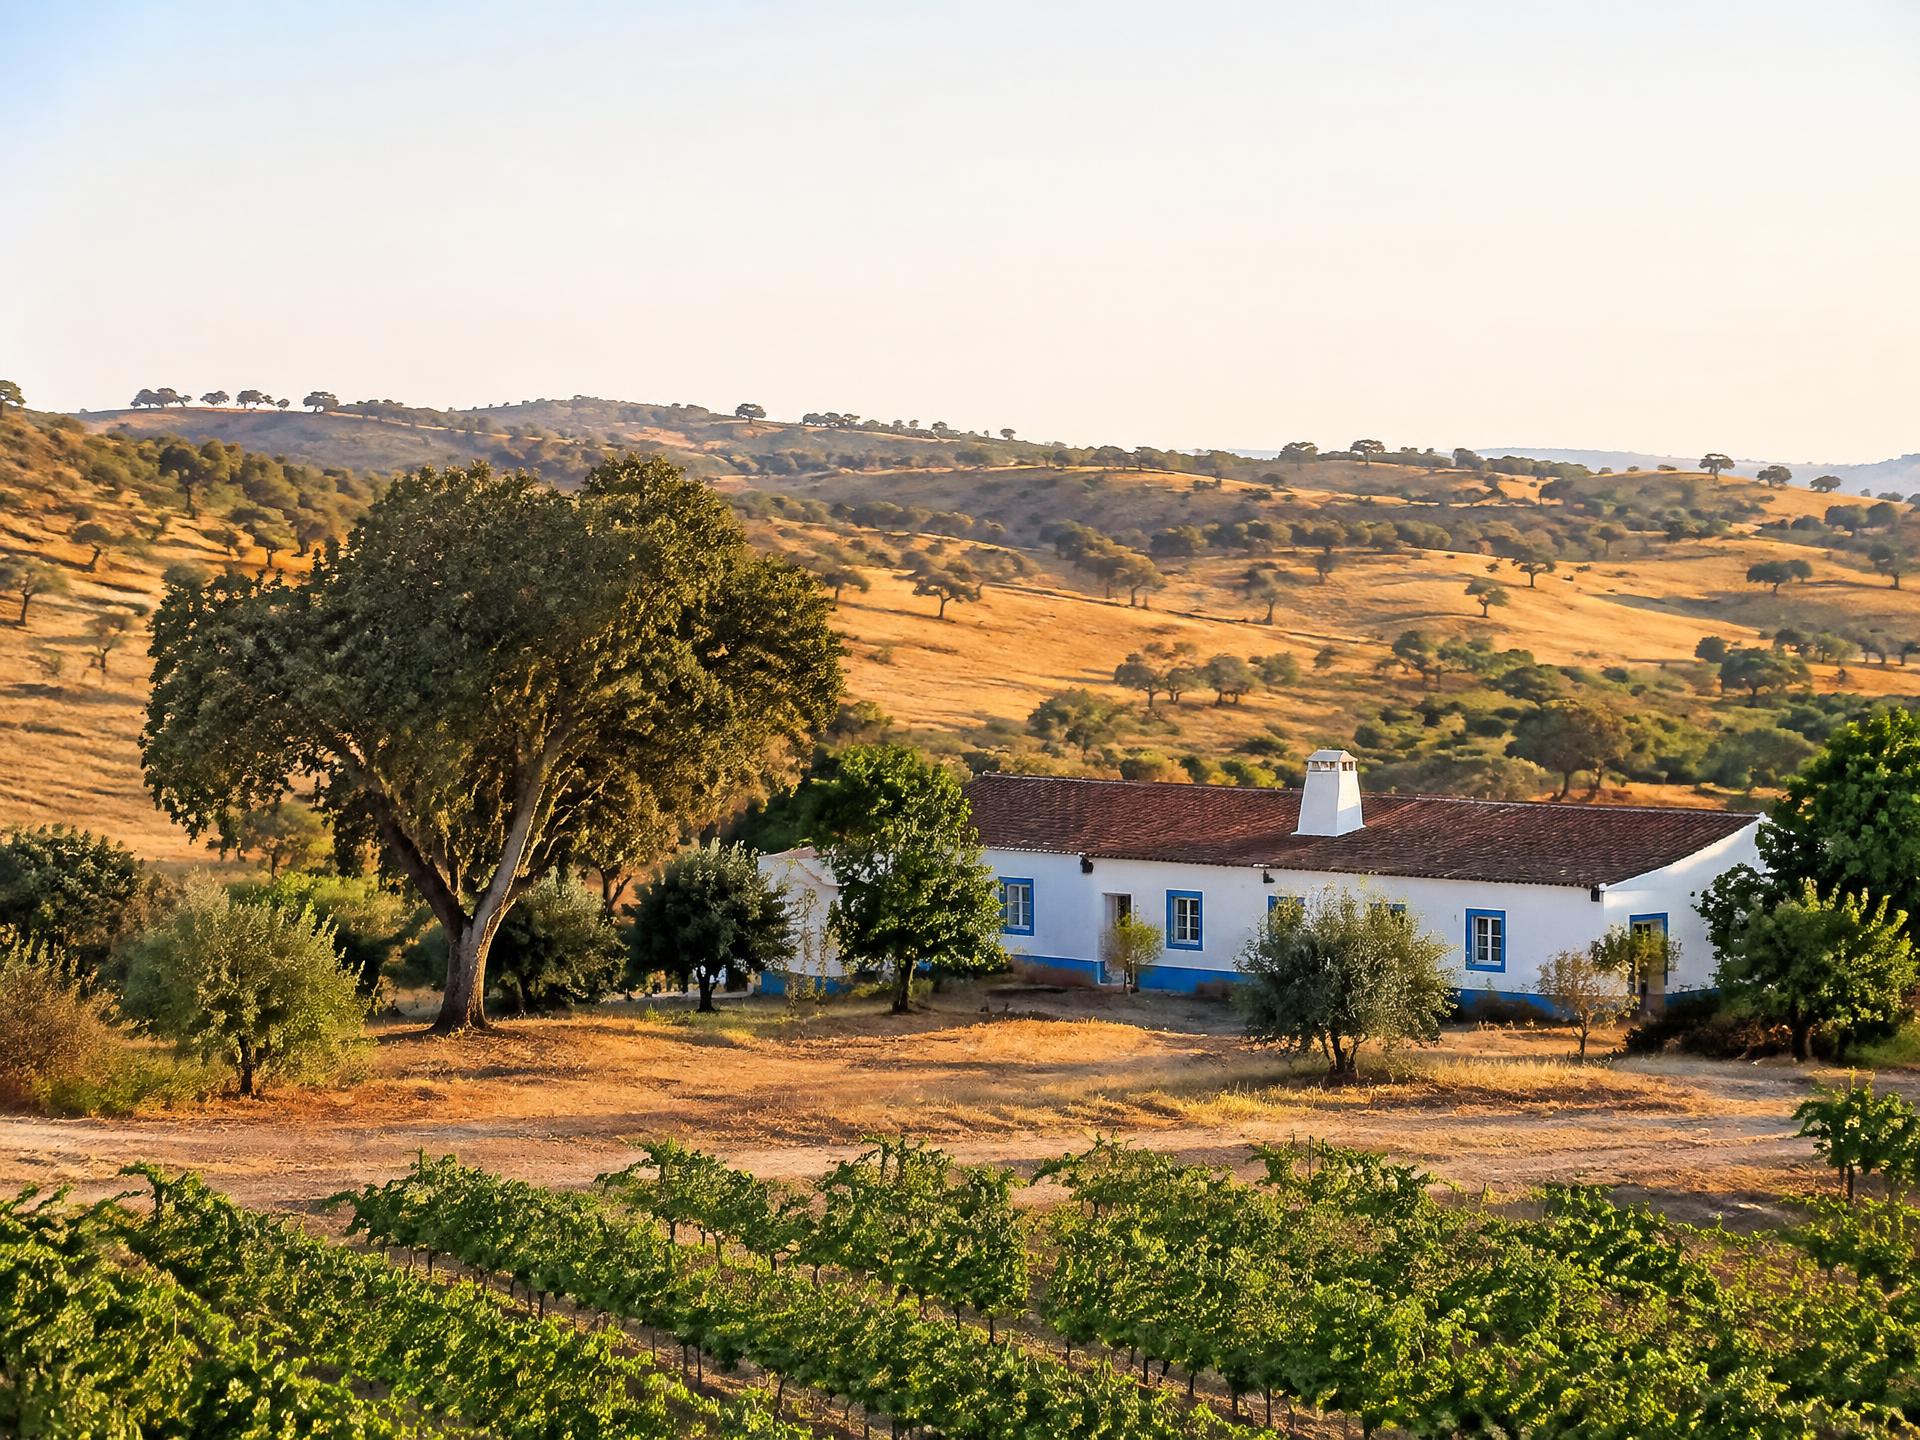
The Alentejo has been establishing itself as one of the most sought-after destinations for investing in rural property in Portugal. Among cork oaks, vineyards and golden plains, the region offers a rare balance between quality of life, appreciation potential and, increasingly decisive, a tax framework that favours investment.
Here are the main advantages and the incentives behind this opportunity.
6 advantages of rural investment in the Alentejo
1. Prices still competitive compared with other regions
Compared with the Algarve or the Lisbon metropolitan area, the Alentejo still offers significantly lower prices per square metre, both for large estates and smaller properties.
2. Strong appreciation potential
The growth of rural tourism and wine tourism has driven consistent appreciation, fuelled by demand from Portuguese and foreign investors.
3. Income diversification
Short-term rentals, rural tourism, farming, olive growing or winemaking can generate multiple revenue streams from the same property.
4. Quality of life and demand for second homes
The calmer pace of life and the authenticity of Alentejo villages attract buyers seeking a life change or a second home.
5. Sustainability and conscious tourism
The region's historic commitment to extensive farming gives the Alentejo an edge as demand for sustainable tourism grows.
6. A particularly favourable tax framework
This last advantage is what most sets the Alentejo apart, and we detail it below.
Tax incentives for investing in the Alentejo
1. Reduced corporate tax (IRC) for inland territories
Companies carrying out agricultural, commercial, industrial or service activities in inland territories, which include much of the Alentejo, may benefit from a reduced IRC rate of 12.5% on the first 50,000 euros of taxable income, under article 41-B of the Tax Benefits Statute. The company must genuinely operate and be effectively managed in the covered territory, a formal registered office in the region is not enough. At the same time, the general IRC rate is falling nationally: 19% in 2026, 18% in 2027 and 17% in 2028.
2. RFAI, Tax Regime for Investment Support
RFAI allows a percentage of investment in productive assets, machinery, equipment, facilities and, in some cases, buildings used for productive activities, to be deducted from IRC. In eligible regions, including the Alentejo, the deduction can reach 25% of relevant investment up to 15 million euros, and 10% on the excess, and may also include exemptions or reductions in IMI, IMT and Stamp Duty. The regime currently runs until 31 December 2027.
3. Enhanced DLRR
The Deduction for Retained and Reinvested Profits lets SMEs deduct from IRC 10% of retained profits reinvested in eligible assets within the following two years, up to 25% of the tax due, rising to 50% for micro and small companies, with a ceiling of 10 million euros per tax period. It can be combined with RFAI for the same investment, within the state aid limits applicable to the region.
4. Portugal 2030 and the Alentejo 2030 programme
The Alentejo 2030 programme regularly opens calls for non-repayable grants for business investment and urban regeneration. A recent example supports small business investments with base funding rates of 50% in low-density territories and 40% elsewhere, plus up to 10 percentage points extra in the Alto Alentejo, classed as a vulnerable territory. There are also calls dedicated to urban rehabilitation and regeneration, particularly relevant for those restoring rural properties or historic centres.
5. 6% VAT on urban rehabilitation
Urban rehabilitation works may benefit from a reduced VAT rate of 6%, under item 2.23 of List I of the VAT Code, a relevant advantage for those restoring rural properties or buildings in historic Alentejo centres. In August 2026, Law no. 48/2026 clarified that this rate applies to works carried out in legally defined Urban Rehabilitation Areas (ARU), regardless of approval of an Urban Rehabilitation Operation (ORU), ending a legal uncertainty dating back to 2009. Even so, it is advisable to confirm the ARU boundaries with the municipality before assuming the reduced rate applies.
Sources: Coverflex · APCMC · Santander Salto · Ordem dos Contabilistas Certificados · Crowe · Deco Proteste.
This article is for information only and does not replace specialised tax or legal advice. The tax regimes mentioned are subject to legislative change, we recommend confirming current figures with a certified accountant or the competent official bodies (Portal das Finanças, Portugal 2030).
Share this article on your social networks